
Boston Area Industrial Market Report for Q4 2026
Overview
ABG Commercial Realty’s Q4 2026 Boston Industrial Market Report
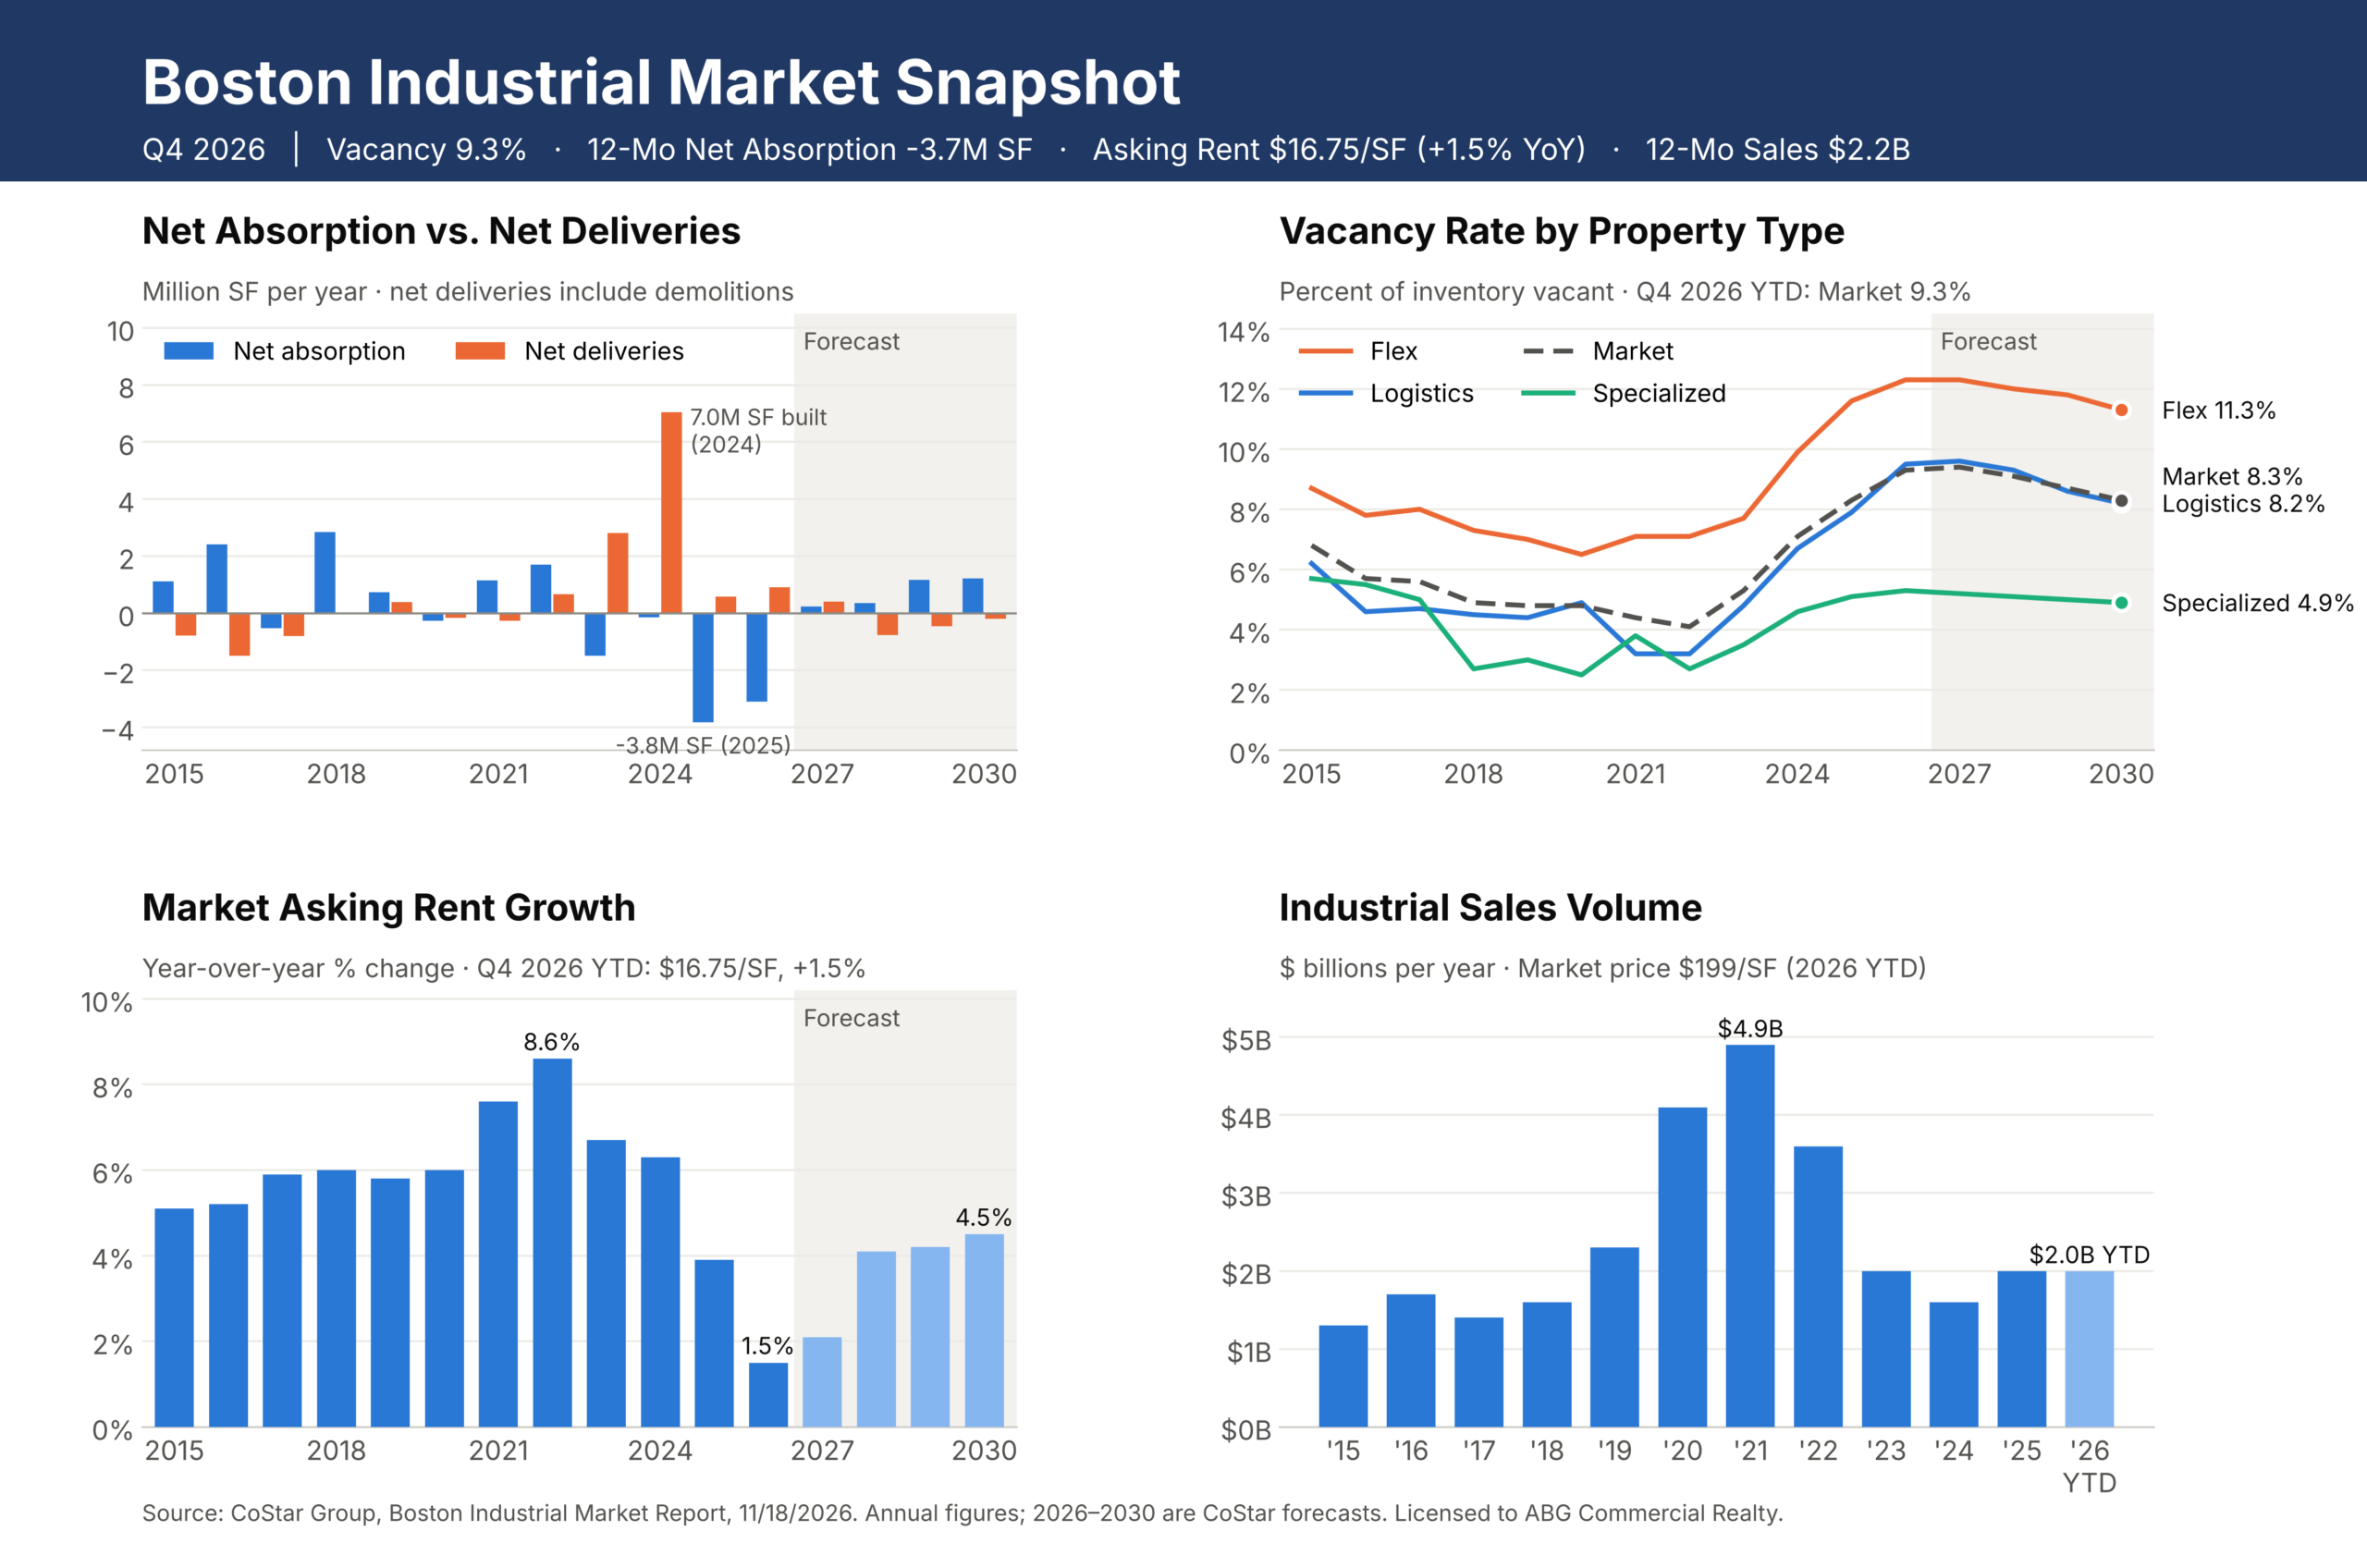
Boston’s industrial market is still dealing with high vacancy, but leasing is starting to pick up. Vacancy is 9.3%, up 1.1 points over the year and well above the record low of 3.6% in mid-2022. Over the past 12 months, net absorption was a negative 3.7 million SF, meaning more space was vacated than leased. Leasing itself is improving: third-quarter volume of about 3.2 million SF was up 45% from a year ago, and 12-month leasing of 11 million SF is about 7% above the three-year average. Most of the large deals have been renewals, with eight of the 10 biggest leases being tenants staying put. New leasing is now picking up, though, and many tenants prefer shorter lease terms to stay flexible.
Results vary a lot by building type and size. Modern logistics buildings are the bright spot. Those built since 2020 with 32- to 36-foot ceilings absorbed about 1.2 million SF, including Amazon’s new 206,000 SF lease in Wilmington. Big-box buildings over 100,000 SF had positive absorption of about 555,000 SF. Small-bay and flex space continued to lose tenants: flex vacancy is 12.3%, logistics is 9.5%, and specialized industrial is tightest at 5.0%. By location, Lowell/Chelmsford and the Route 3 Corridor gained occupancy, while Peabody/Salem and Route 24 each lost more than 500,000 SF.
Rent growth has slowed to 1.5% a year, down from a peak of 8.7% in 2022, and the average asking rent is about $16.75/SF. Flex rents grew fastest, about 3.1%, to around $20/SF. Big-box logistics rents grew 2.9%, while small-bay rents dipped 0.5%. Sublease space is listed at discounts of $2.80–$3.25/SF below direct asking rents, which gives tenants more room to negotiate. New construction has slowed to 3.1 million SF underway, down from 8.7 million SF at the end of 2022. However, about 91% of that space has no tenant lined up yet, so it could push vacancy up as it comes online. At the same time, about 1.4 million SF of older small-bay and flex buildings has been demolished this year.
Investors are still active. Sales volume reached $2.2 billion over the past 12 months, above the three-year average of $2.0 billion, and third-quarter sales were up 21% from a year earlier. Boston industrial prices average about $199/SF, well above the national average of about $153/SF. Institutional investors now make up 50% of buyers, mostly targeting newer, fully leased logistics buildings. CoStar expects vacancy to level off in 2027 and start falling in 2028 as available space gets leased.
Looking for industrial space or thinking about selling? Whether you need warehouse, flex or logistics space, or want to know what your property is worth in today’s market, the ABG Commercial Realty team is here to help. Contact us today for a free consultation and a custom market analysis.